


Lincoln Financing Options for Luxury SUV Buyers
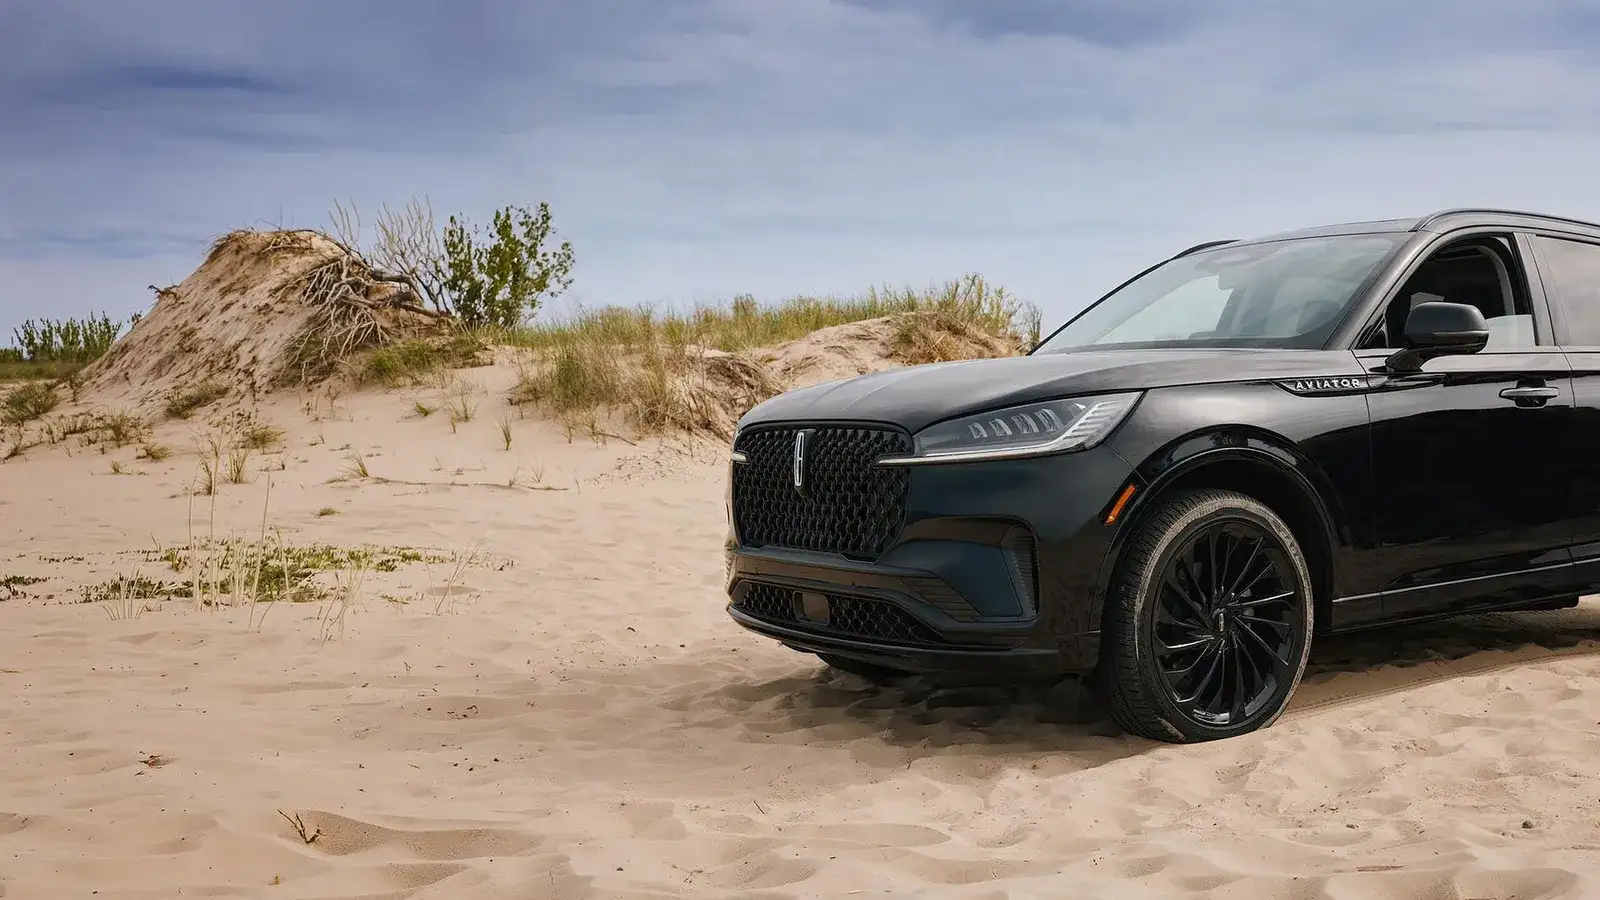
A morning trip from Rancho Mirage to Palm Springs feels different when the vehicle fits the life you have built – and so should the payment plan behind it. Lincoln financing options are not one-size-fits-all. The right choice depends on whether you value long-term ownership, a lower-term commitment, the flexibility to change vehicles often, or the added reassurance that comes with a certified pre-owned Lincoln.
For many Coachella Valley shoppers, the decision is not simply loan versus lease. It is about matching a Navigator, Aviator, Nautilus, or Corsair to how you drive, how long you plan to keep it, and what you want premium ownership to feel like. A clear conversation about financing should make that decision easier, not more complicated.
Lincoln Financing Options: Loan, Lease, or Certified Pre-Owned?
The three most common paths are financing a new Lincoln with an auto loan, leasing a new Lincoln, or financing a certified pre-owned Lincoln. Each has a place, and none is automatically the “better” choice for every driver.
With a traditional loan, you make payments toward ownership. Once the loan is paid in full, the vehicle is yours, and you can keep it, trade it, or sell it when the time is right. This approach often suits drivers who expect to enjoy their Lincoln for many years, drive more than a typical lease allowance, or want the freedom to customize their ownership timeline.
A lease provides the use of a new Lincoln for an agreed period, usually with a set annual mileage allowance and condition requirements at lease-end. Because you are paying for the vehicle’s use during the lease term rather than its full purchase cost, leasing can be appealing for shoppers who prefer driving newer models more frequently. It can be especially attractive when your priorities include current design, the latest driver-assist technology, and a predictable changeover schedule.
Certified pre-owned financing is a compelling middle ground. A Lincoln that has been carefully selected, inspected, and tested can give you access to premium features and refinement with a different ownership entry point than a new vehicle. It may be a smart fit if you plan to own rather than lease, want a well-equipped model, and appreciate the confidence that comes with manufacturer-backed certification standards.
A quick answer: should you lease or finance a Lincoln?
Lease a Lincoln when you prefer a new vehicle every few years, have a reasonably predictable driving routine, and are comfortable with mileage and wear guidelines. Finance a Lincoln when you want to build ownership, drive without lease mileage limits, or keep the vehicle after payments are complete. Certified pre-owned financing can be ideal for buyers seeking long-term luxury ownership with a later-model vehicle.
Start With Your Driving Life, Not a Monthly Payment
A monthly payment matters, but it should not be the only number guiding your choice. Focusing only on a payment can hide the factors that shape the overall agreement: term length, amount financed, down payment or trade-in value, available incentives, interest rate, mileage allowance on a lease, and the anticipated value of the vehicle later.
Begin with how you actually use your SUV. A Palm Desert family that carries guests, golf bags, and luggage for weekend trips may gravitate toward the expansive space of the Lincoln Navigator. An Aviator may make more sense for a household that wants three-row flexibility in a more manageable footprint. The Nautilus provides a confident, comfortable choice for daily commuting and highway travel, while the Corsair fits drivers looking for luxury in a more city-friendly SUV.
Then consider your ownership horizon. If you see yourself in the same Lincoln well beyond the final payment, financing may align naturally with that plan. If you enjoy moving into a fresh model as technology and design evolve, a lease can preserve that flexibility. Neither decision needs to be permanent: many drivers begin with a lease and choose to purchase their Lincoln at the end if it has become the right long-term vehicle.
How Trade-Ins and Down Payments Shape Your Options
A trade-in can play an important role in your next Lincoln arrangement. Its value may be applied toward a purchase or lease, potentially reducing the amount you finance or the amount due at signing. If you have equity in your current vehicle, it can give you more flexibility in selecting a term or structuring a lease.
A larger down payment can also reduce the financed balance and, in many cases, the monthly payment. But putting more down is not always the only sound approach. Some buyers prefer to keep more cash available for other priorities, especially when a trade-in has already contributed meaningful value. The best structure is the one that supports your broader financial comfort, not simply the lowest possible payment on paper.
Bring a realistic picture of your current vehicle, credit profile, and preferred budget range to the conversation. A finance professional can explain the available scenarios without making assumptions about what luxury ownership should look like for you.
Lease Details That Deserve a Closer Look
Leasing is straightforward when its terms reflect your habits. Before choosing a lease, talk through expected annual mileage honestly. Regular drives from Indio to Los Angeles, frequent desert road trips, or a long commute can add up faster than expected. A higher mileage allowance may be a better fit than trying to force an active driving life into a lower allowance.
Also ask about the vehicle’s expected return condition. Normal wear is different from damage, and understanding that distinction before you sign helps avoid surprises later. At lease-end, you generally have options: return the vehicle, purchase it if the agreement allows, or transition into another Lincoln.
For Black Label shoppers, leasing can be a thoughtful way to experience Lincoln’s highest level of design, materials, and personalized ownership benefits while retaining the option to move into a newer Black Label model on a planned schedule. Financing may be preferable if you have found a particular Black Label configuration you expect to cherish for years. It depends less on the badge and more on your ownership plans.
Financing a Certified Pre-Owned Lincoln
A certified pre-owned Lincoln deserves more than the label “used.” Certification is designed to provide additional peace of mind through a detailed inspection process and program benefits that distinguish it from an ordinary pre-owned vehicle. For buyers comparing a new Corsair or Nautilus with a certified pre-owned Aviator or Navigator, this creates a useful decision point: do you prioritize the newest generation and full choice of configurations, or a later-model vehicle that may offer a different set of features and ownership value?
Financing terms for certified pre-owned models can differ from new-vehicle offers, so it is worth reviewing both paths side by side. Compare the total term, estimated payment, coverage details, anticipated maintenance needs, and how long you intend to keep the SUV. A vehicle with the right history, condition, and equipment can be a more satisfying choice than selecting only by model year.
What Lenders Commonly Review
When you apply for auto financing, lenders commonly consider credit history, income, current debt obligations, employment information, residence history, the vehicle selected, and the amount being financed. A stronger application can sometimes open more choices, but shoppers across a range of credit situations deserve a respectful, transparent discussion of their options.
If you are rebuilding credit, have recently changed jobs, are self-employed, or are considering a co-applicant, say so early. These details are not reasons to avoid the process. They help the finance team identify documentation and lending paths that may fit your circumstances. Being prepared often makes the experience more efficient and less stressful.
It can help to gather a current driver’s license, proof of income, proof of residence, insurance information, and details for any trade-in before you visit. If you are applying jointly, both applicants should be ready to provide the relevant information. A pre-approval can clarify your range before you choose a specific vehicle, although final terms are typically tied to the selected Lincoln and completed application.
Questions to Ask Before You Sign
A good financing conversation leaves room for questions. Ask whether the quoted payment reflects the exact term you discussed, what amount is due at signing, whether there is a prepayment penalty on a loan, and what happens at the end of a lease. If you have a trade-in, ask how its value is being applied. If you are comparing terms, ask to see how a shorter and longer loan term change the payment and total cost of financing.
For a lease, confirm the annual mileage allowance, excess-mileage terms, vehicle condition expectations, and purchase option at the end of the agreement. For a certified pre-owned Lincoln, ask about the vehicle’s inspection, coverage, service history, and available financing programs.
The goal is not to rush into the first arrangement presented. It is to understand the choices well enough to select one confidently. Premium service should include clear answers, whether you are considering your first luxury SUV or returning for your next Lincoln.
When you are ready, explore new and certified pre-owned Lincoln options, bring your trade-in questions, and apply for financing with a plan that feels comfortable. At Palm Springs Lincoln, the next step can be as simple as a conversation and a VIP test drive – with the time and clarity to find the Lincoln that belongs in your life.
Frequently Asked Questions
What is Lincoln Automotive Financial Services?
Lincoln Automotive Financial Services is Lincoln’s own finance company. It offers retail financing for new, certified pre-owned and used vehicles, as well as the Lincoln Red Carpet Lease for new models. Arranging it through the dealership lets you compare Lincoln programs with other lender options in one conversation, with approval based on your application.
Are Lincoln finance and lease offers the same everywhere?
No. Lincoln offers often vary by region, model, trim, term and credit approval, and they change from month to month. A program advertised nationally may not apply in Southern California, or may require qualifying credit. Check the current offers for the Coachella Valley and ask how a specific offer applies to the exact Lincoln you want.
How is sales tax handled on a Lincoln lease in California?
In California, sales tax on a lease is generally charged on the monthly payments and certain amounts due at signing rather than on the full vehicle price at once. The exact amount depends on where you live and how the lease is structured. Ask for an itemized lease worksheet that shows tax, fees and the payment.
Can I end a Lincoln lease early?
It is often possible, but early termination can be costly because the remaining payments and the vehicle’s value still have to be settled. Some drivers trade into a new Lincoln before the term ends when their equity position allows it. Review the early termination section of your lease and ask for a payoff quote before deciding.
0 comment(s) so far on Lincoln Financing Options for Luxury SUV Buyers